Paul Cavey
East Asia Today
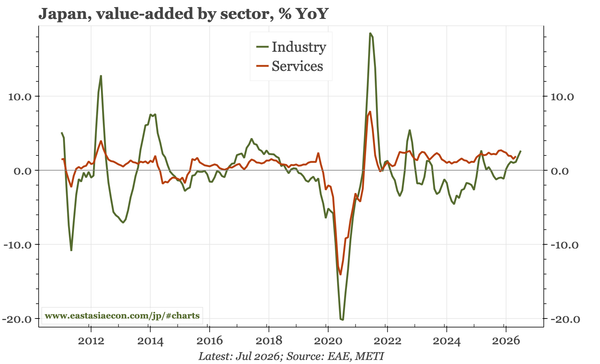
Lot of data released in China, none of which show any change in the story. Japan's service growth remains strong, but manufacturing output is now also rising too. August terms of trade data in Korea indicate yet faster nominal GDP growth in Q3. Outbound FDI in Taiwan remains strong.
China – still no break
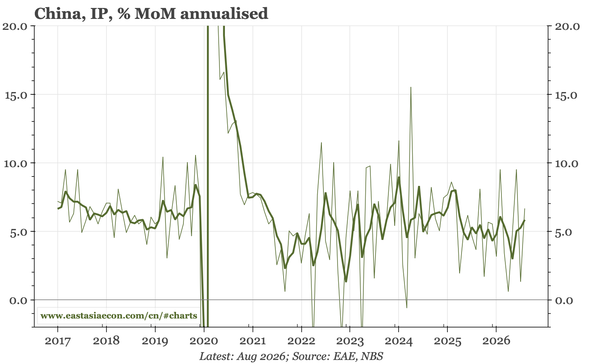
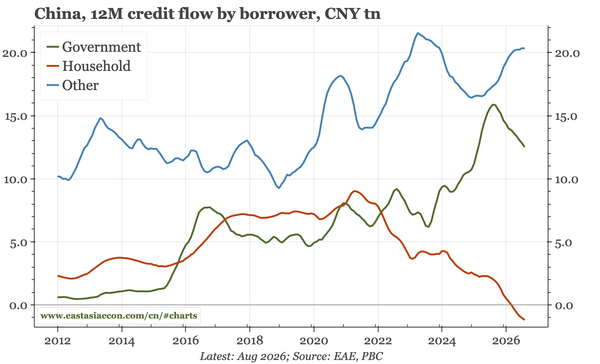
Domestic demand remains soft, with no break in the property market collapse. But helped by exports, IP is growing near 6% saar, which keeps the GDP growth target for this year in reach. So I doubt much changes in terms of policy, but the emerging weakness in services is something to be monitoring.
Korea – the rising tide
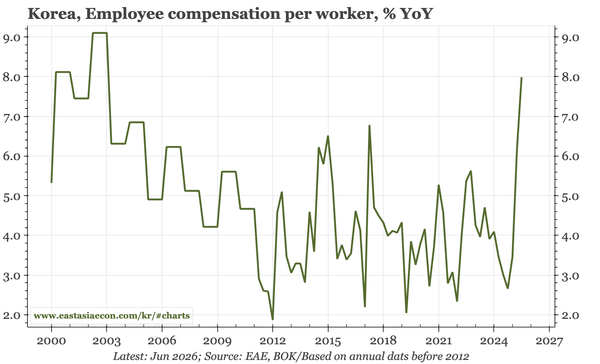
Last week's GDP data showed nominal growth of over 25% YoY in Q2. Most of that was in the form of corporate profits, but employee compensation still rose 8% YoY. With the government planning growth in fiscal spending of 12% in 2027, there are more signs of the IT sector lifting the broader economy.
East Asia Today
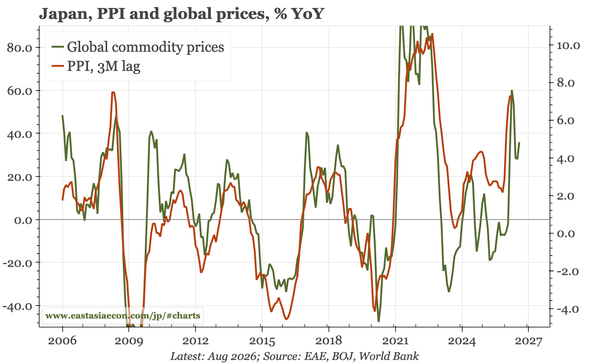
Korean BOP data for August, an update on upstream prices in China, which have been stronger than I had been expecting, and PBC liquidity operations through August. Foreign exchange reserves in Taiwan rebounded in August. I am away next week, so the next update will be Monday 14th September.
Korea – from selling to buying
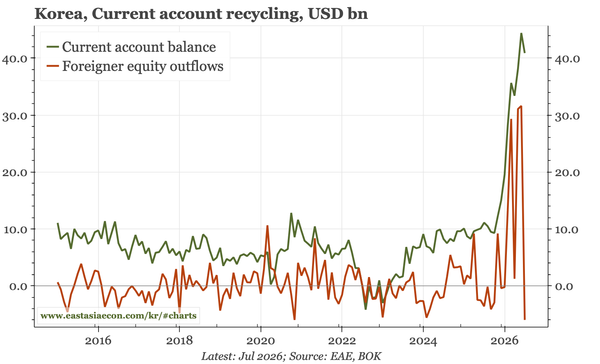
Today's BOP data show that after selling more than USD30bn of domestic equities in June, foreigners purchased USD6bn in July. That swing goes a long way to explain the sudden appreciation of the KRW. That should be able to continue, given CA surplus of over 20% of GDP, strong economy, and BOK hikes.
East Asia Today
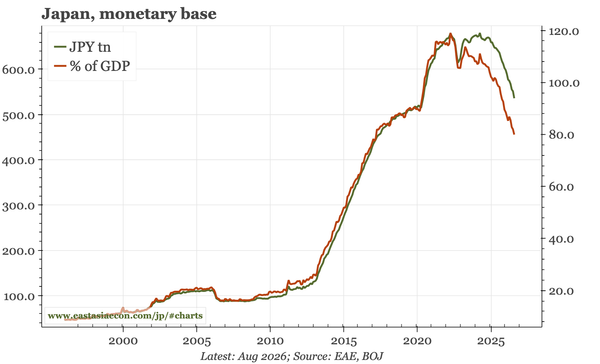
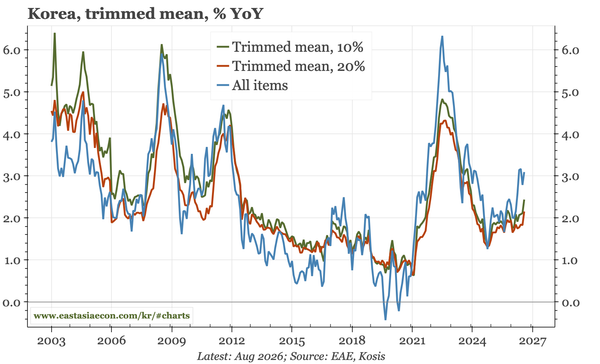
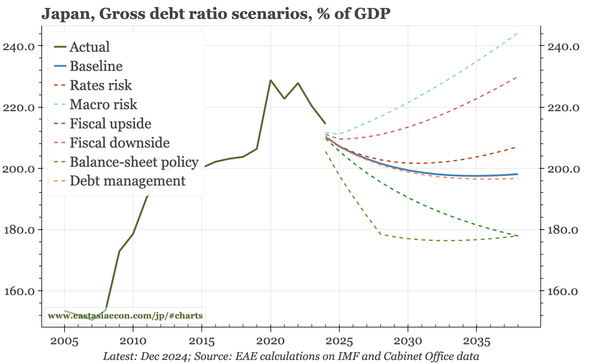
The main release today was Korean CPI inflation for August, which remained firm. Japan tax revenue ticked down last month, but the uptrend of recent years remains intact. However, the monetary base is falling fast. Also today, a comprehensive guide and online model to Japan's fiscal position.
East Asia Today
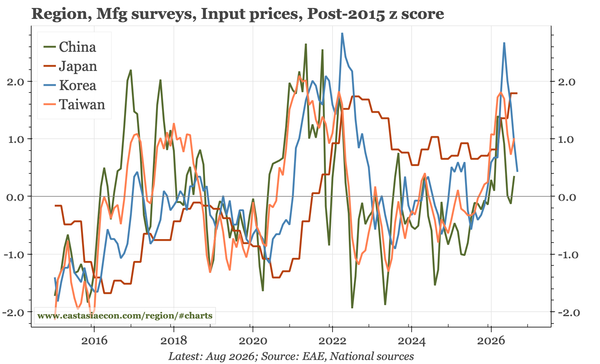
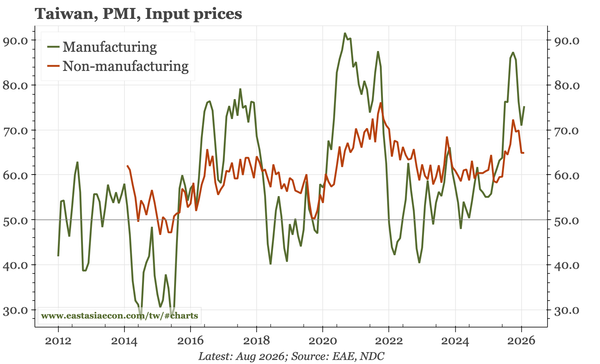
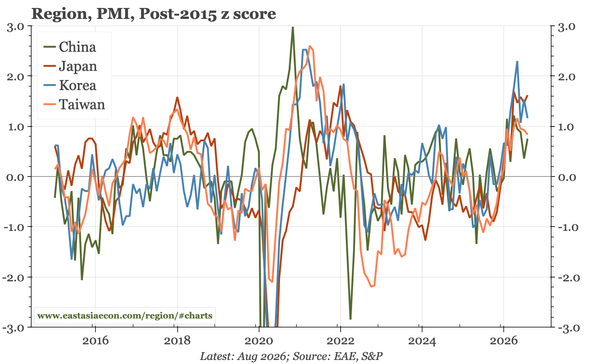
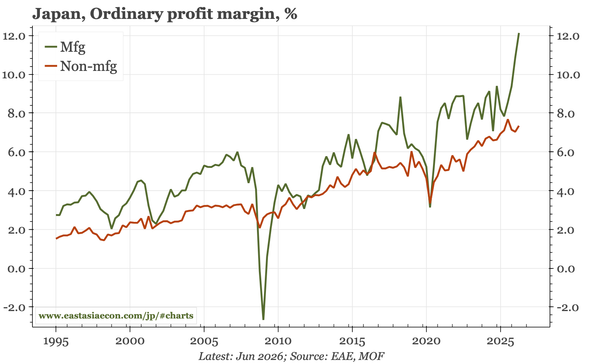
A busy day of data today, with regional PMIs, Q2 profits data for Japan, and foreign trade in August for Korea. Japan is leading in both relative manufacturing activity and prices. Taiwan activity is also strong, and not benefiting from the ccy appreciation that is dampening input prices in Korea.
Region – Japan leading
The PMIs show Japan's manufacturing cycle is the strongest in the region. That might be because the measures in Taiwan and Korea struggle to capture the macro impact of chip strength. Even so, it is still an important take-away, especially when the PMIs show Japan also leads in price strength.
Japan – mfg mini-boom
Defying BOJ fears of a slowdown, this year's surge in corporate profits continued in Q2. The big driver this year has been manufacturing, and today's PMI shows the recovery in the sector isn't over yet. Relative to the strength of profits, capex and wages are sluggish.
Korea – strong July
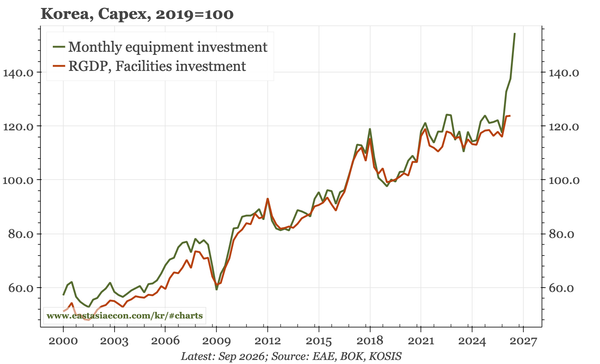
Output in July retained the gains of June, and capex spending rose further. Both suggest a strong start for GDP in Q3. Retail sales were weaker last month, but the household sector should start to benefit as the government spends the 20% growth in tax revenue of recent months.
China – no change
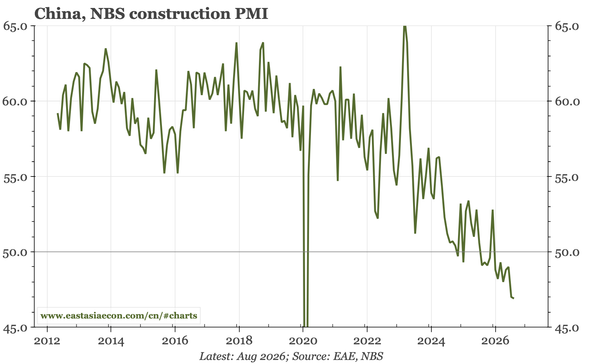
The PMIs continue to show no economic cycle. Construction activity continues to drop, but the manufacturing PMI continues to hover around the 50 mark. Input prices have rebounded again, so this year's recovery in PPI isn't ending just yet. None of these changes point to a shift in policy.