Paul Cavey

Paul Cavey

East Asia Today

East Asia Today

A longer piece on how the impact of pricier energy imports is being offset by big increases in electronics export prices. Today's data releases showed competing cycle indicators in Japan: strong bank lending versus a weak EW survey. Some contradictions also in Korea, with low UE, but soft wages too.
3 min read

Region – the other terms of trade shock

Region – the other terms of trade shock

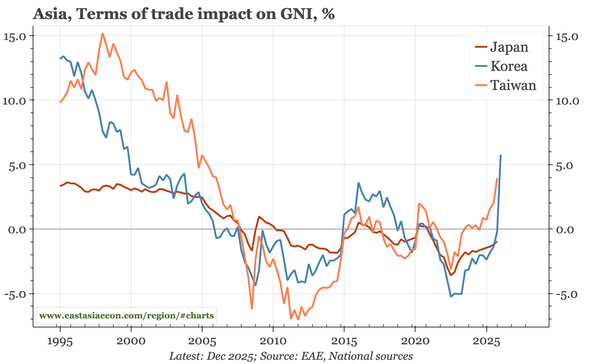
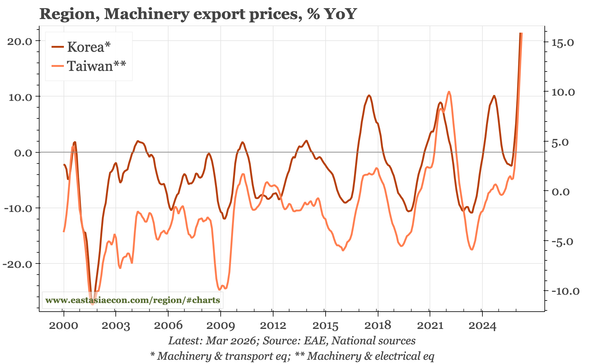
The Iran War will push up inflation. But for growth, transmission is via the terms of trade, and higher import prices are being offset by historical rises in export prices, increases that are unlikely to be just cyclical. That supports growth in Asia, at the expense of even more inflation for ROW.

8 min read

East Asia Today

East Asia Today

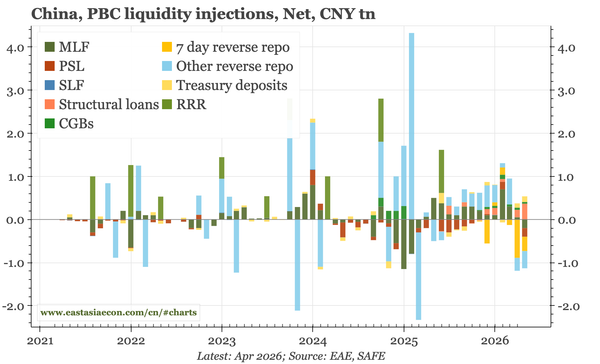
Signs of less loosening in China, in both the PBC monetary policy report for Q126, and the April release of the central bank's liquidity operations. In Japan, the summary of the April MPC show more pressure to tighten. Consumption data for March and trade data for early April were stable.

2 min read

East Asia Today

East Asia Today

China CPI and PPI data for April showed a further strengthening of inflation. Korea's trade data for the first 10 days of May indicate no slowdown in semi exports (or rise in energy imports). Data for Taiwan through March point to a slowdown in wage growth in recent months.

3 min read

China – inflation up again

China – inflation up again

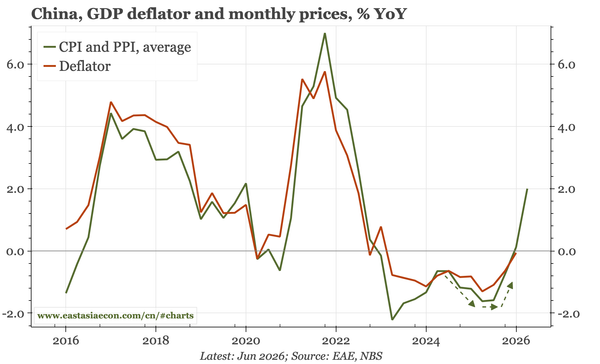
PPI inflation accelerated again in April, and with CPI inflation firm, the GDP deflator is on track to rise in Q2 for the first time in 2022. The turn is being led by energy and commodity prices. There are some signs of a stabilisation in underlying prices too, but so far, they are tentative.

3 min read

Last week, next week

Last week, next week

Stabilisation in China seems to be becoming a more popular view. Hope is building for a BOJ hike in June, but one won't be enough. KRW should be strengthening, but likey needs more Middle East certainty. The big event for the region this week is the Xi-Trump meeting.

7 min read

China – imports strong again

China – imports strong again

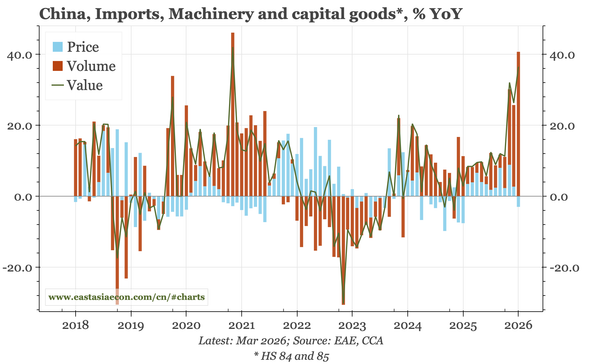
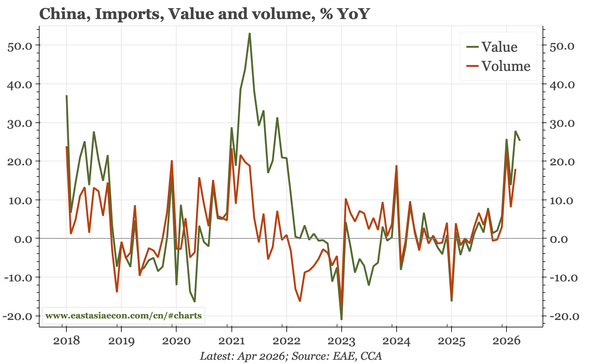
After doing nothing for 3 years, imports are suddenly growing 20%. Chips are one component, but while I thought that related to prices, official data show the bigger diver of overall imports is volumes. I am not sure that's because of domestic demand, but it is starting to reduce the trade surplus.

2 min read

East Asia Today

East Asia Today

Korea March data finally showed a fall in offshore buying by residents, only to be replaced by domestic selling by foreigners. Taiwan's April trade data show limited Iran impact. Japan wage growth in March was strong, but only at the headline level. And my latest video, on why Taiwan macro matters.

3 min read

Taiwan – limited impact yet

Taiwan – limited impact yet

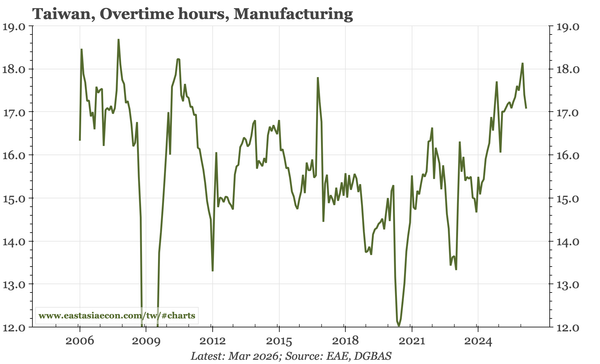
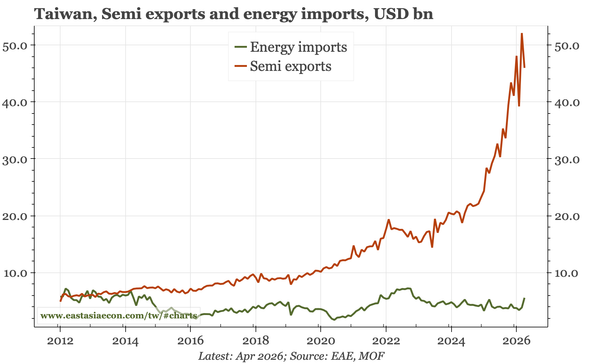
April trade data show little damage from the Iran war. If the crisis remains limited to energy prices, Taiwan should be somewhat insulated. Energy imports are small relative to chip exports, and while import prices will rise, export prices are now also increasing for the first time in a generation.

3 min read

Korea – from foreign buying to foreigner selling

Korea – from foreign buying to foreigner selling

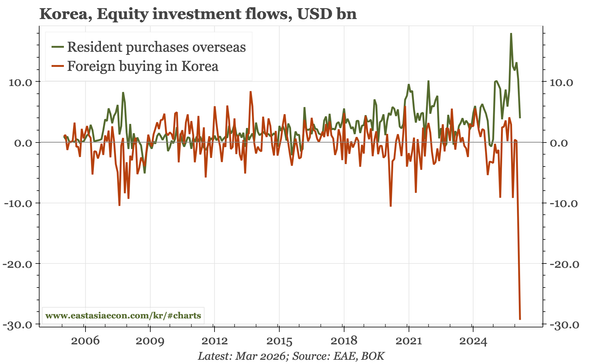
March data offer more evidence that the KRW just can't get a break. Finally, retail outflows into foreign assets eased, only to be replaced by huge domestic selling by overseas investors. That has normalised in April, so perhaps investors are realising that a CA surplus of 20%+ of GDP should matter

2 min read

East Asia Today

East Asia Today

Highlights of longer notes on the regional outlook, and growth trends in Korea. Also, a summary of today's inflation data in Taiwan, where import prices are rising, but export prices are too. Finally, high-frequency upstream price data in China, and the April monetary base update in Japan.

3 min read

Korea – semi still offsetting energy

Korea – semi still offsetting energy

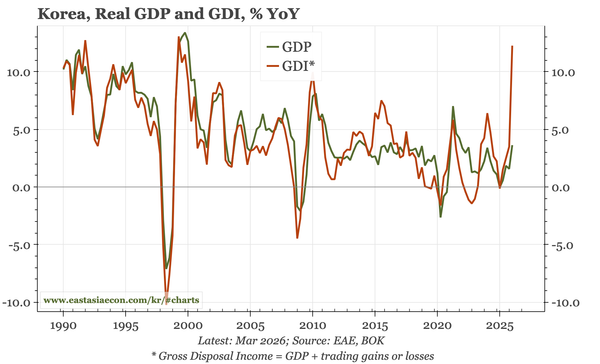
The BOK's current forecast assumes no GDP growth in the rest of the year, and contracting exports. But export growth still looks to be picking up, capex indicators are improving, and there is a tailwind from growth in real Gross Domestic Income in Q1 being faster than any time since the 1990s.

4 min read

Region – slide pack

Region – slide pack

With the full consequences of the Iran War yet to be felt, the outlook remains uncertain. But so far, upside risks to inflation in the region are dominating the downside risks to growth. The big driver is the semiconductor cycle. The pack starts with regional themes, then 15 charts for each economy.

3 min read