Paul Cavey
East Asia Today
The highlight today was the BOJ governor's speech, which I thought was about as hawkish as it could be. In China, while the official services PMI last month was weak, the RatingDog/S&P version was strong. Also in China, PBC liquidity withdrawals suggest May was another strong month for fx inflows.
Japan – Ueda stresses inflation risks
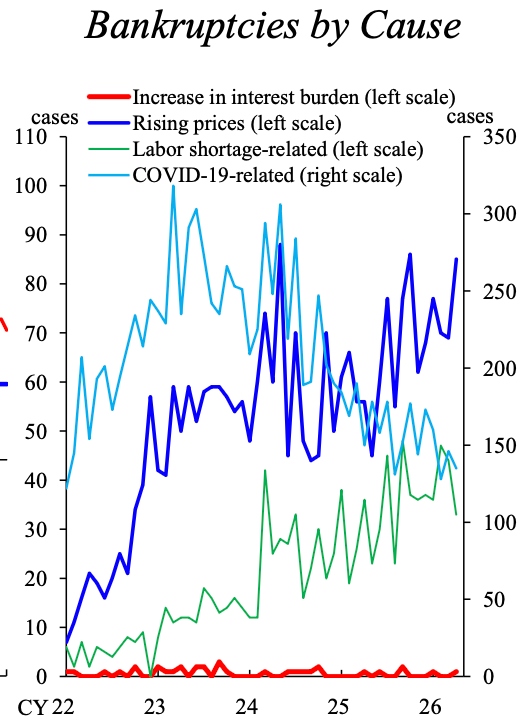
Some highlights from governor's speech today: his remarks about strong bank lending, higher prices being a bigger burden to firms than rising rates, the link between low policy rates and the rise in market yields, and the upside risks to prices now that the "deflationary mindset has been dispelled".
East Asia Today
A review of today's CPI release in Korea, a video discussing the market and macro consequences of the chip cycle, and some charts on the last trade release for April in China covering prices and volumes. Also, three charts highlighting why Governor Ueda's speech tomorrow is so important.
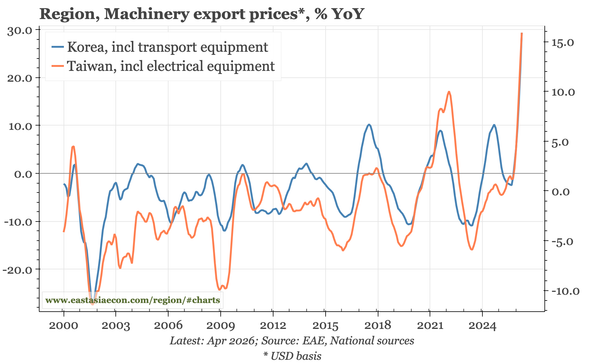
Region – understanding Asia's chip cycle
My latest video, a discussion of everything you need to understand the macro implications of the huge chip cycle – what's driving it, why prices and volumes matter, the role of China, the growth and inflation consequences, and what it all means for markets.
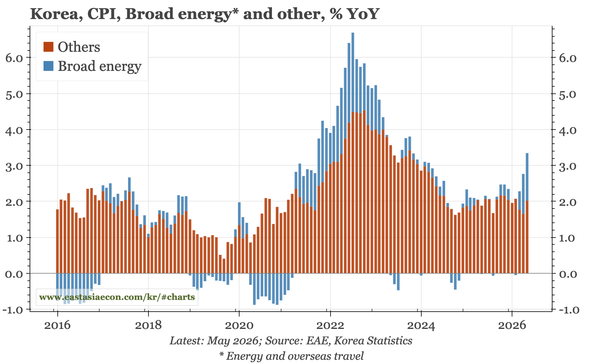
Korea – CPI still mainly energy
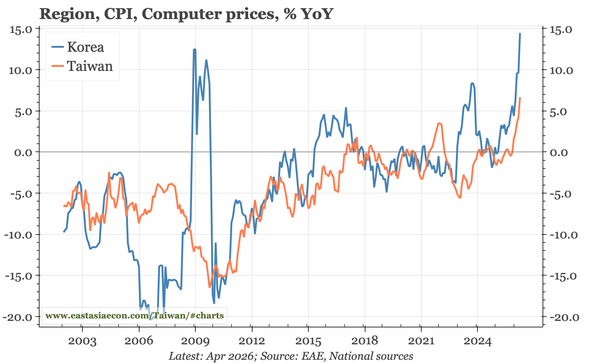
The rise in inflation is mainly about energy. But that headline inflation is now above 3% YoY – and private services over 4% – also reflects two other drivers: a high starting point, and the rise in chip prices that via cost-push is showing up in the CPI in higher prices for electronic devices.
East Asia Today
The PMIs point to strong demand in Taiwan and Korea, supply disruptions in both economies and Japan, and elevated price pressures everywhere. In China, the same themes are apparent, but not to the same extent. Also today, Japan Q1 profits, Korea May trade data, and a strong non-mfg PMI in Taiwan.
China – no big change in PMIs
In today's official data, headline PMIs for both manufacturing and services remain around 50. The details of the manufacturing PMI don't suggest much Middle East disruption. The run-up in prices that pre-dated Iran is, however, sustaining. On the other hand, employment remains weak.
East Asia Today
Highlights of three longer notes today: a thematic look at the regional drivers of inflation (it isn't just energy); mixed end-month data in Korea; and very strong Q1 GDP in Taiwan, with a bullish government forecast for 2026. Also, some charts summarising all the many data releases today in Japan.
Taiwan – growth up, now inflation too
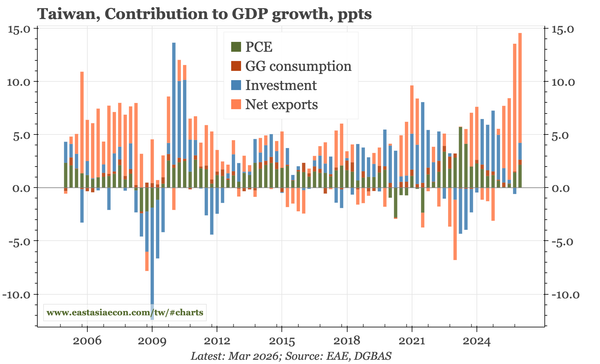
Today's Q1 GDP data show the economy growing more quickly than any time in over 40 years. The government thinks that continues: in the forecast, downside risk from Iran isn't mentioned, but trickle down from semi to the real economy is. CPI was also revised up, even if it remains (just) below 2%.
Korea – mixed month-end data
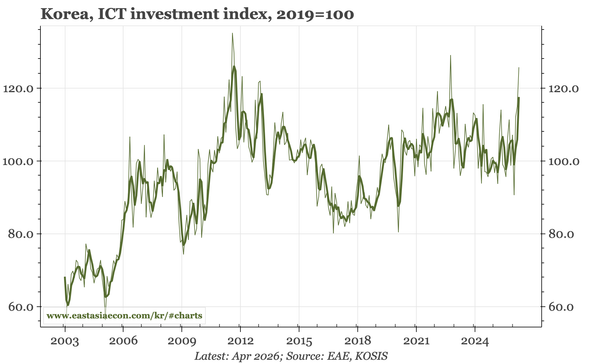
Two of the key issues for the economy are whether the chip boom trickles down, and what damage the Iran war will cause. April data show a bit of both. ICT capex rose for the third month, and there were more signs of a floor in the labour market. Overall output fell, but remained above the Q1 average
Region – inflation risks
Big oil price hikes matter, but have been seen before. It is the rise in chip prices, and the gap between surging trade surpluses and weak currencies, that is unprecedented. If fx markets don't price these developments, central banks and fixed income will have to do so instead.
East Asia Today
The BOK meeting was the main event today. For releases across the region, it has been a quiet day. Taiwan's monitoring indicator in April stayed in the range that represents "economic boom". Export data for the first ten days of May in Japan were stable, but Toyota sales in April were weaker.
Korea – everything but a hike
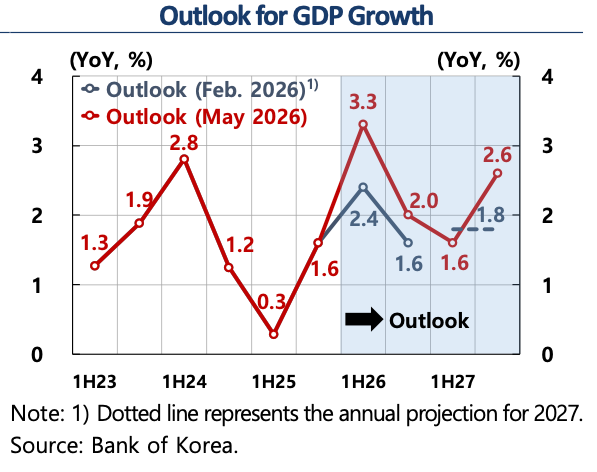
The BOK didn't change rates today, but signalled that despite continued uncertainty, higher rates are coming. The pace will depend on dynamics in the energy and chip markets. I would also be watching for how core CPI performs against the BOK's modest forecast of 2.4%