Paul Cavey
Last week, next week
China's cycle is weak, but I'm not yet convinced it is getting worse. Japan's cycle will now be improving, but the BOJ needs to show that it can keep up. The BOK's hawkish turn can go further still if the KRW remains so weak. I think inflation risks in Taiwan are broader than judged by the CBC.
East Asia Today
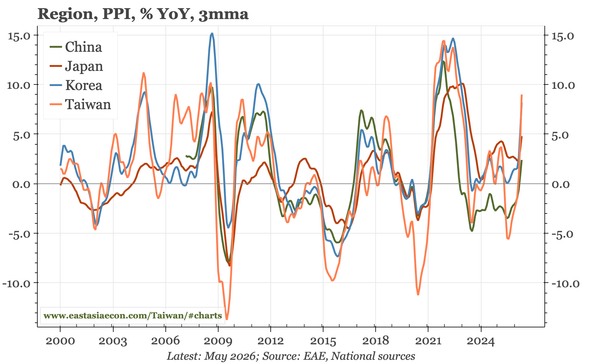
A new video laying out my argument for stabilisation in China. In terms of the data flow, Japan's inflation was modest in May, but that was because of subsidies, and further JPY depreciation will push up prices again. Korean PPI inflation accelerated, with the jump most obvious in services.
China – is (it still possible) the worst is over?
My latest video, making the case for a bottoming of China's economy. In light of this week's poor official data, the argument might look off-base, which means it should at least be interesting. I do think the logic holds up, but as discussed here, there are reasons I could be wrong.
East Asia Today
A quiet day, because no policy change from Taiwan's CBC, and no major releases elsewhere. China did release more detailed trade data for May, and in the context of renewed worries about growth, it is important that the broader import growth of this year has persisted.
East Asia Today
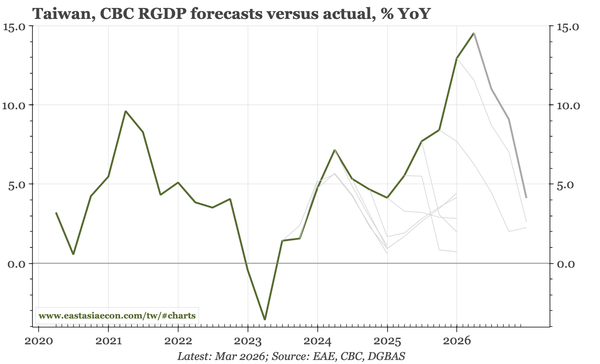
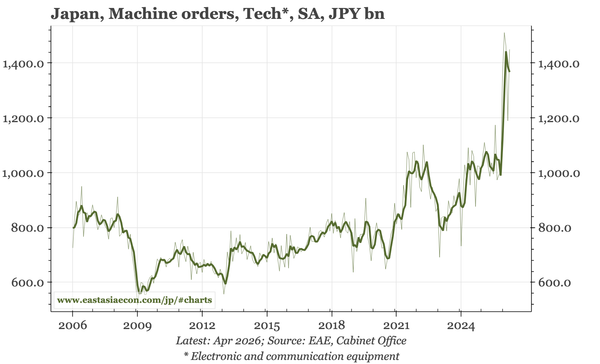
Highlights of a longer note reviewing the cycle in Taiwan before the central bank's meeting tomorrow. In Japan, machine orders, exports and the Reuters Tankan all point to a strengthening manufacturing cycle on the back of global AI demand. Also, some charts on upstream prices in China.
Taiwan – is there a reason not to hike?
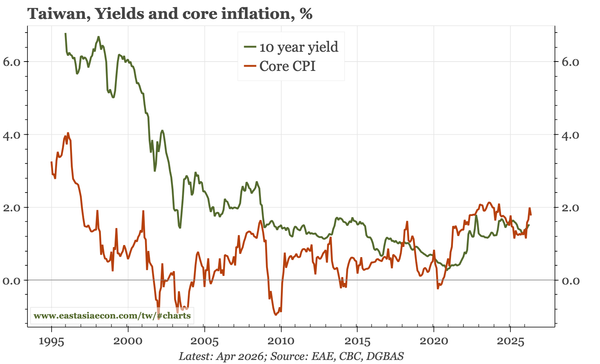
Core inflation has rarely been higher, the export economy is booming, and signs are emerging of stronger domestic demand. Core inflation is still only 2%, but yields are even lower (!), and there's plenty of asset price inflation in stocks. Hence the question: why wouldn't the CBC hike tomorrow?
East Asia Today
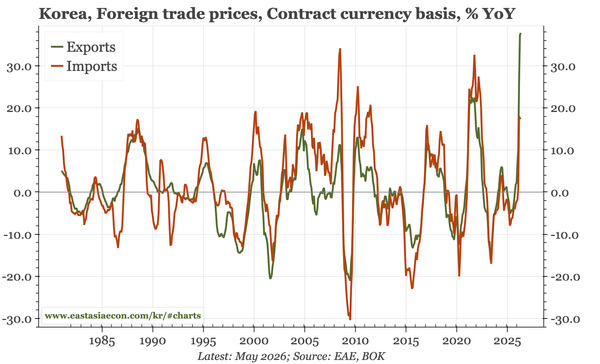
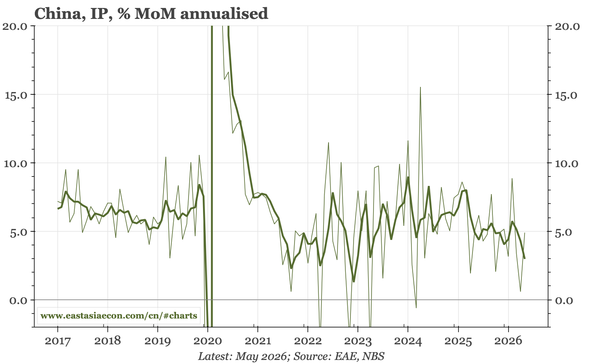
Another round of bad economic data in China. The BOJ raised rates today, with little reaction in either equities or fx, suggesting with rates at 1% monetary policy still remains very accommodative. In Korea, rather than higher import prices, it is the rise in export prices that is more significant.
Korea – export prices still the standout
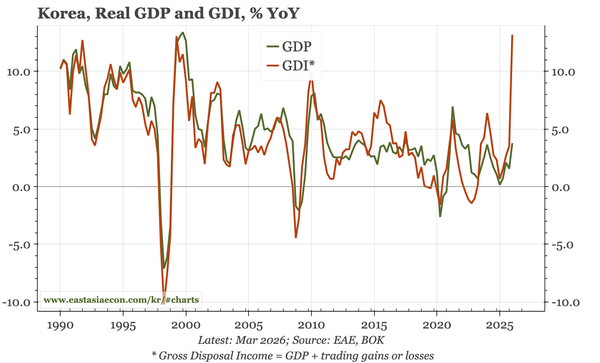
The sharp rise in import and export prices of recent months eased in May. But that leaves export prices at the highest level since the brief spike in 2008. That brings inflation for ROW and an income boost for Korea. With spot semiconductor prices still rising, neither trend is yet exhausted.
China – another month of weak data
I have been arguing that the underlying economy has been stabilising, with prices bottoming out before the Iran war. But stabilisation is external-led, and today's data show the domestic cycle remains a mess. That will likely become a policy issue if IP doesn't stay at an annualised run-rate of 5%
East Asia Today
On Friday BOK governor Shin Hyun Song gave a short but interesting speech. Today's main release was China's May fx settlement data, indicating that the pace of net capital inflows remains solid. Taiwan's annual IIP data show that despite the huge CA surplus, net foreign assets fell in 2025.
Korea – Shin's surer
BOK governor Shin Hyun Song gave a speech on Friday to mark the 76th anniversary of the bank's founding. It was short, but worth highlighting, because he sounded more confident about the outlook, and downplayed the significance of uneven growth as a factor for monetary policy.
Last week, next week
Three themes: whether the weakness in the activity data releases of a month ago in China was noise; Japan, where one hike is unlikely to be enough to really change market conditions; and the semi super cycle, which should be having more impact on fx and rates (in Taiwan) than has yet been evident.