Paul Cavey
East Asia Today
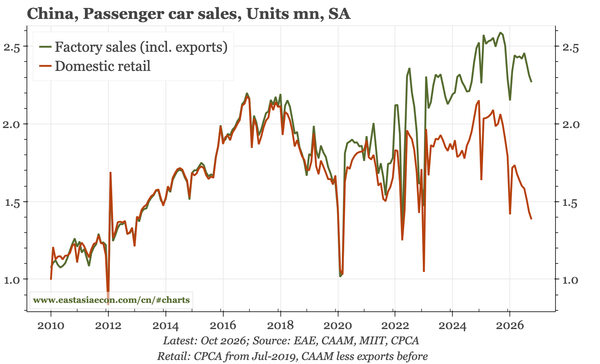
An update on domestic auto sales in China through the first couple of weeks of November, machine orders in Japan, and net foreign assets. Also, a write-up of the BOK's monetary policy report, which in English is released only with a lag, but shows why the bank was confident in September.
Korea – more BOK optimism
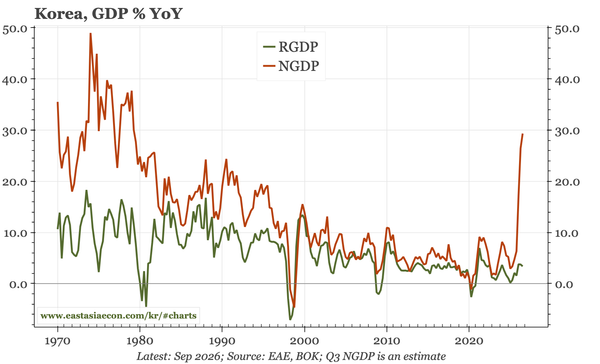
The BOK's latest MPR, including a focus on the "surge in NGDP" shows again the bank's optimism. That tone isn't new, but the confidence matters, especially as it is based on a belief that the cycle isn't as narrow as usually perceived. The caveat is this report was published in Korean in September.
East Asia Today
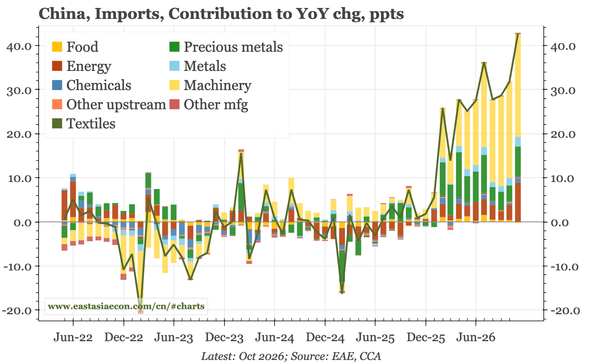
Detailed trade data for China show a slowdown in car exports. Probably, that is a cause. In Japan, by contrast, auto exports have started to show signs of life. Non-mortgage borrowing in Korea did fall in Q3, but the big change in household debt ratios came from the surge in nominal GDP.
East Asia Today
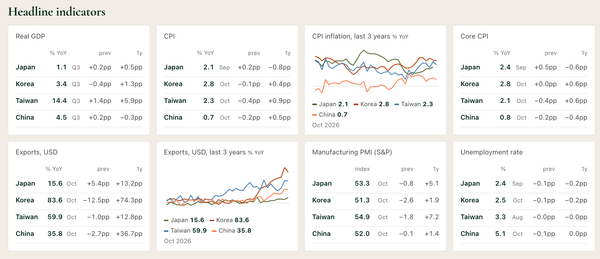
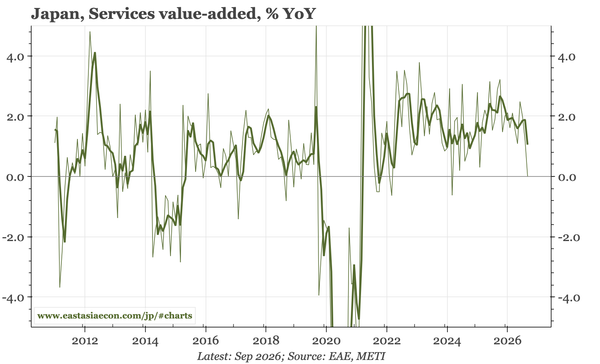
The only release today was Japan services activity, worth highlighting because of the sharp slowdown the last couple of months. China's fx settlement data yesterday were, by contrast, strong. Also, re-launching my website, redesigned as a more effective dashboard for monitoring the region.
East Asia Today
Except for IP, Oct data in China were weak. Japan's Q3 GDP was also soft, though that was all because of consumption and imports; capex was up. Korean full-month trade data show Korea's auto sector isn't yet suffering the China Shock 2.0. FDI in Taiwan continues to move from China to the US.
China – no change in macro
The macro story continues to be real weakness in lots of economic data, except industrial production. As long as that is growing near 5%, the government likely thinks the economy is fine. That said, the decline in M1 growth points to slower nominal momentum in 2027, making PBC easing more likely.
East Asia in Four Charts
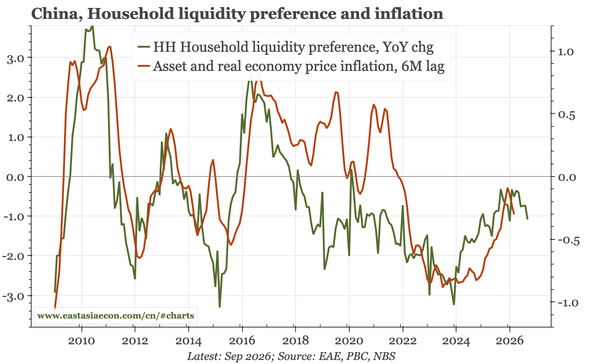
China's domestic reflation is slowing. Japan's reflation is alive, though the last sign that deflation is over – firms becoming net borrowers – hasn't happened yet. Korea's terms-of-trade windfall may be peaking, but Taiwan's trade data show global tech demand in October was still strong.
Last week, next week
Asia faces not one but two sources of external pressure: the Nvidia fall-out, and expectations for tighter monetary policy. Demand has been strong through November, so there is still room for CBs to hike with the Fed. That, however, isn't true in China, which contrasts with bullish CNY sentiment.